The short answer: Rhode Island's real estate conveyance tax is $3.75 for every $500 of the sale price, or $7.50 per $1,000, and the seller pays it unless the contract says otherwise. On homes selling for more than $824,000 in 2026, a second tier adds another $3.75 per $500 on the amount above $824,000.
Last updated: . Rates verified against R.I. Gen. Laws § 44-25-1 and Division of Taxation Advisory 2026-01.
How the Rhode Island conveyance tax works
Every deed recorded in Rhode Island for more than $100 carries a conveyance tax under R.I. Gen. Laws § 44-25-1. People call it the transfer tax, the deed stamps, or the documentary stamps; the statute calls it the real estate conveyance tax. It is due when the deed is presented for recording, and it is collected by the city or town clerk in the municipality where the property sits, whether that is Providence, Cranston, Warwick, or a town in South County. The clerk affixes a receipt to the deed showing the tax paid.
Two details surprise people. First, the tax is charged on the whole price, and the statute counts any lien or encumbrance that stays on the property as part of that price. Second, it is computed per $500 or fractional part, so a price that is not a round number rounds up to the next $500 increment.
The money does not all stay local. Of each $3.75, the statute sends $0.50 to the state's distressed community relief program, $0.50 to the housing resources and homelessness account, and $0.95 is retained by the state. The remaining $1.80 stays with the city or town that collected it.
What it costs: worked examples
Here is the Rhode Island tax at six price points, using the rates in effect for 2026, next to what the same sale would cost in Massachusetts (outside Barnstable County) for anyone weighing a move across the line from Attleboro, Seekonk, or the SouthCoast.
| Sale price | Rhode Island tax (2026) | Massachusetts deeds excise |
|---|---|---|
| $350,000 | $2,625 | $1,596 |
| $500,000 | $3,750 | $2,280 |
| $650,000 | $4,875 | $2,964 |
| $824,000 | $6,180 | $3,757.44 |
| $1,000,000 | $8,820 ($7,500 + $1,320 second tier) | $4,560 |
| $1,500,000 | $16,320 ($11,250 + $5,070 second tier) | $6,840 |
Rhode Island figures assume a residential sale with no lien remaining on the property. The second tier applies only to residential real property. Massachusetts figures use the $2.28 per $500 rate (including the 14% surcharge) stated in Massachusetts DOR Directive 95-4; Barnstable County is lower.
The details that change the number
The October 2025 rate increase
Until September 30, 2025, the rate was $2.30 per $500. The state's FY2026 budget (P.L. 2025, ch. 278) raised it to $3.75 per $500 effective October 1, 2025. On a $500,000 sale that is the difference between $2,300 and $3,750. If you priced a sale using a net sheet from before last October, rerun it.
The second tier on homes over $824,000
Since January 1, 2022, residential sales above a threshold have paid a second layer of tax on the amount over that line. The threshold started at $800,000. The 2025 amendment indexed it to inflation (CPI-U), rounded up to the nearest $5 and never allowed to decrease, and the Division of Taxation set it at $824,000 for calendar year 2026. The second-tier rate is also $3.75 per $500, and it is charged in addition to the regular tax, only on the portion above the threshold. That revenue is earmarked for housing: $2.50 of each $3.75 goes to the state housing production fund.
For higher-priced homes, from Providence's East Side to Barrington and Newport County, the second tier belongs in the net sheet from the start. The threshold resets every January, so confirm the current year's figure before closing.
Who pays, and when it is negotiable
The statute is plain: "In the absence of an agreement to the contrary, the tax shall be paid by the grantor," meaning the seller. Buyer and seller can agree otherwise in the purchase and sale agreement. Whatever the agreement says should be written into the contract, not left to the closing table.
What is exempt, and what is not
Section 44-25-2 lists only a handful of exemptions. The ones most people will ever encounter:
- Mortgages and refinances. Any instrument given to secure a debt is exempt.
- Deeds from a government grantor. When the United States, the State of Rhode Island, or a city or town is the seller.
- Transfers for $100 or less. The tax only applies when the consideration exceeds $100, and a no-consideration deed must say so on its face.
Just as important is what is not on the list. There is no first-time homebuyer exemption and no general exemption for transfers between family members in the statute. Those questions turn on the consideration actually paid, which is where attorney review of the deed earns its keep.
Moving from Massachusetts? Two differences to know
Massachusetts calls its version the deeds excise (M.G.L. c. 64D, § 1). Beyond the lower rate, Massachusetts computes it on the price excluding any lien that remains on the property, while Rhode Island includes it. And the Massachusetts statute does not say who pays; Rhode Island's does. Anyone who has sold in Massachusetts and is now selling in Rhode Island, or relocating along the I-95 and I-195 corridors in either direction, should expect this line on the closing statement to be larger on the Rhode Island side.
Frequently asked questions
Who pays the real estate transfer tax in Rhode Island?
The seller. R.I. Gen. Laws § 44-25-1 makes the grantor responsible in the absence of an agreement to the contrary, so the parties can agree to split or shift it in the purchase and sale agreement.
How much is the transfer tax on a $500,000 home in Rhode Island?
$3,750. The rate is $3.75 for each $500 of the price, or $7.50 per $1,000. A $500,000 sale is below the $824,000 second-tier threshold, so nothing more applies.
What is the second-tier tax on homes over $824,000?
On residential property, an additional $3.75 per $500 applies to the part of the price above $824,000, the 2026 threshold. It is added on top of the regular tax. The threshold is indexed to inflation each January and can only go up.
Is there a first-time homebuyer exemption from the transfer tax?
No. Chapter 44-25 contains no first-time homebuyer exemption or credit. The statutory exemptions cover things like mortgages and deeds from government grantors.
Is there transfer tax on a mortgage or refinance?
No. Section 44-25-2 exempts any instrument given to secure a debt, so recording a mortgage does not trigger the conveyance tax.
Know your number before you list or offer
The conveyance tax is one line on a closing statement, but on a sale over $824,000 it can be the difference between accepting an offer and countering it. If you are selling, we will run a net sheet for your property with the current rate and threshold built in. If you are buying, we can tell you whether any of it is on the table in your deal.
Search Rhode Island homes for sale Ask us to run your numbers
This article is general information about Rhode Island law as of the date above, not legal or tax advice for a particular transaction.
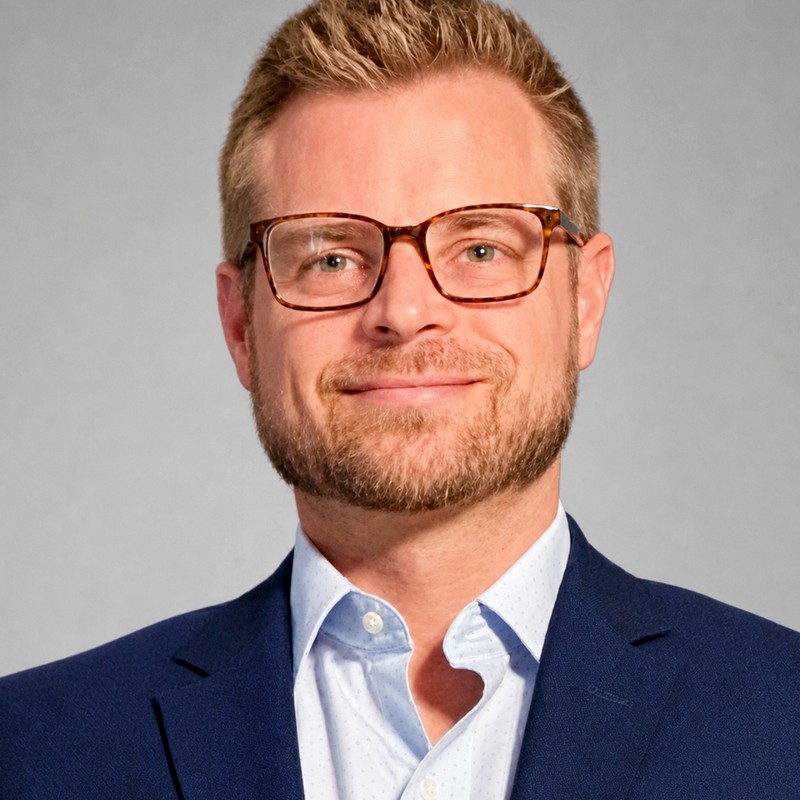
Tom Thomasian is a co-founder of Realty Quarters, a real estate broker, and an attorney admitted in Rhode Island and Massachusetts in 2007 after earning his J.D. at Roger Williams University School of Law.
Read Tom's full bio →